Before placing machinery in Germany for stock or demonstrations, identify the owner, importer, seller and demonstration operator. Then align tax, site capability and the first customer delivery. We can coordinate our German warehouse and showroom, agreed commercial representation, and entity/VAT arrangements. Receipt, energisation and live trials each require a product-specific scope.
A packaging machine, laser cutter or production unit may remain a demonstration asset for months or become a customer delivery within days. Decide what this particular machine is for before comparing storage prices. A German address alone does not settle its ownership, tax treatment or acceptance.
Map the transaction before dispatch
Record the contracting seller, stock owner, importer and final destination. A customs representative, storage operator and buyer may be different parties. Receiving the crate does not itself transfer ownership or establish entitlement to input-tax deduction.
German UStG section 3 governs goods-supply location; section 15 sets input-tax conditions. Have the actual contracts and import documents reviewed. A business customer’s VAT number does not automatically make every German domestic machinery sale VAT-free or reverse-charged: section 13b needs a separate applicability check.
| Commercial situation | Input needed | Decision before shipment |
|---|---|---|
| Unallocated stock | Owner, import authority, intended destinations | Importer, tax responsibilities, stock records |
| Customer order held temporarily | Contract, delivery terms, payment and acceptance | Separate receipt from customer acceptance |
| Long-term demonstration asset | Configuration, use, site and operating conditions | Permitted activity, operator, insurance, disposal |
| Supply with installation or modification | Work scope and site requirements | Separate technical and tax classification review |
Separate arrival cash from economic cost
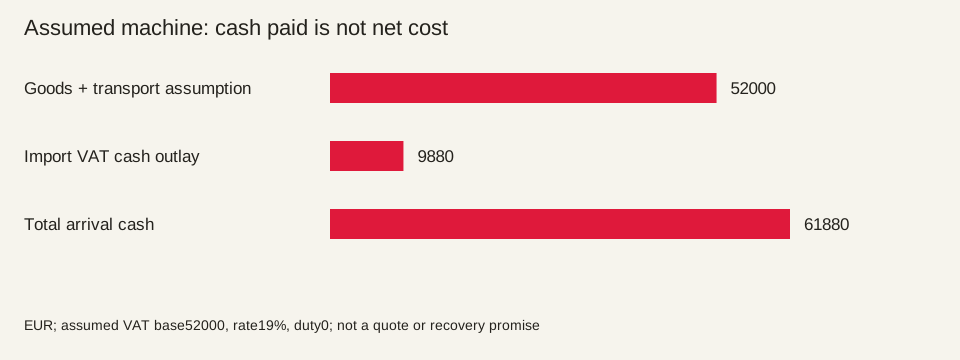
For an invented budget, assume an import-VAT base of EUR 52,000 including the assumed machine/transport amounts, a 19% rate and zero duty. Import VAT is EUR 9,880 and arrival cash totals EUR 61,880. Actual classification, valuation, duty, incidental costs and payment arrangements must be checked for the shipment. This is not a service quote.
If the legal conditions and documentation support deduction, VAT may have a different economic treatment from irrecoverable operating costs. It can still absorb cash. This calculation promises neither deductibility nor a recovery date; an incorrect importing entity or missing documents cannot be solved by simply labelling VAT refundable.
Import VAT changes the stock-funding requirement
Budget unloading equipment, storage, insurance, repacking, dispatch and site work separately. State whether each charge is per unit, visit or period. Agree what happens if a viewing is cancelled, stock remains unsold or the unit has to return: who authorises the next action and pays for it?
Define what the customer will actually see
An external inspection, a static technical discussion and an energised material trial are different assignments. Obtain the machine dimensions, mass, lifting points, power/media requirements, instructions, protective arrangements and manufacturer support. Available floor space is not evidence that a site can safely operate that model.
If a buyer wants to verify accuracy, cycle time or yield, agree the material, program, fixtures, instruments, sample count, acceptance criterion and signatory. We can coordinate the agreed reception, schedule, documents and commercial discussion. Authorised competent parties remain responsible for technical trials, compliance, operation and acceptance. A demonstration video is not a certification report.
| Viewing level | Confirm beforehand | Useful output |
|---|---|---|
| External/configuration review | Model, serial number, permitted access, confidentiality | Photos, configuration and open questions |
| Static technical meeting | Manufacturer engineer, drawing revision, language needs | Recorded questions and written answers |
| Energised/material trial | Site, operator, safety, material, acceptance method | Agreed trial record, not a certification claim |
| Quotation follow-up | Pricing, discount and commitment authority | Controlled quote and next action |
Convert the demonstration unit into a delivery
When the unit sells, reconfirm the contracting seller, demonstration history, condition, accessories, software rights, warranty start, training and payment. Logistics booked for a showroom do not automatically cover unloading or connection at the buyer’s factory.
Distinguish loading, arrival, installation, commissioning and customer acceptance. Identify manufacturer inputs, buyer site preparations and each local assignment. Obtain professional review of tax classification and applicable local requirements rather than inferring them from the storage arrangement.
Price the local assignment precisely
Tell us whether you need stockholding, showroom presentation, representation at a named trade fair, or authorised follow-up with identified buyers. For a fair, define the event, exhibits, materials and on-site duties. For sales representation, agree customer ownership, quotation authority, contract signature and payment flow. We do not promise sales.
We review warehouse, showroom and local support against the product and assignment before agreeing execution and fees. Local presence does not mean every machine can be installed, tested or repaired at the site.
Send a machine brief for scope review
Send the model, dimensions, mass, ownership/import plan, target customer and expected German holding period. Specify external viewing or live trial, and your existing entity, VAT and contract position. We can then align the entity/tax work with storage, presentation and authorised commercial support, with unconfirmed site tasks listed separately.
Sources and checks
Checked: 2026-10-30